What an extra $100, $250 or $500 a month does to your mortgage
Every extra dollar toward your mortgage saves interest, but not every dollar saves the same amount. How much you save depends on three things: the size of the extra payment, how early in the loan you start, and your interest rate. The size gets all the attention. The timing and the rate matter more than most people expect.
1. The example loan
A $300,000 loan at 6.5% over 30 years. The principal and interest payment is $1,896.20 a month, and paying it on schedule costs $382,637 in interest. (Property tax, insurance and PMI would sit on top of that payment. They don't change the interest math, so they're left out here.)
2. How much each extra amount saves
| Extra a month | Debt-free | Time saved | Interest saved | Interest saved per extra $1 |
|---|---|---|---|---|
| $50 | 27 yr 10 mo | 2 yr 2 mo | $33,582 | $2.02 |
| $100 | 26 yr | 4 yr | $60,996 | $1.96 |
| $250 | 21 yr 10 mo | 8 yr 2 mo | $120,339 | $1.84 |
| $500 | 17 yr 6 mo | 12 yr 6 mo | $179,761 | $1.72 |
| $1,000 | 12 yr 9 mo | 17 yr 3 mo | $241,165 | $1.59 |
Two things stand out. First, small amounts add up: $100 a month, about what a few streaming subscriptions cost, takes four years off the loan and saves about $61,000. Second, the returns taper off. Each dollar saves less as the extra payment grows, because a bigger extra payment pays the loan off sooner, and there is less time left for interest to pile up.
3. Timing matters more than amount
Take the same $250 a month, but start it at different points in the same loan:
| Start $250 extra | Balance then | Time saved | Interest saved | Interest saved per extra $1 |
|---|---|---|---|---|
| On day one | $300,000 | 8 yr 2 mo | $120,339 | $1.84 |
| After 5 years | $280,833 | 5 yr 11 mo | $78,731 | $1.38 |
| After 10 years | $254,329 | 4 yr 1 mo | $47,108 | $0.99 |
| After 15 years | $217,679 | 2 yr 8 mo | $24,618 | $0.67 |
| After 20 years | $166,998 | 1 yr 6 mo | $10,118 | $0.40 |
The same $250 a month saves twelve times as much on day one as it does after 20 years. Early in a loan, most of each payment is interest, so a dollar of extra principal removes a long stretch of future interest. Late in a loan, there's little left to remove. If you can only afford extras for part of the loan, the early years are when they work hardest.
4. Your rate changes everything
The same $250 a month on a $300,000, 30-year loan at different interest rates:
| Interest rate | Interest on schedule | Time saved | Interest saved | Interest saved per extra $1 |
|---|---|---|---|---|
| 3% | $155,333 | 7 yr 2 mo | $40,716 | $0.60 |
| 4.5% | $247,219 | 7 yr 6 mo | $69,860 | $1.04 |
| 6.5% | $382,637 | 8 yr 2 mo | $120,339 | $1.84 |
| 8% | $492,470 | 8 yr 9 mo | $168,164 | $2.65 |
The time saved barely changes, but the money saved does, because the same months are worth a lot more interest at a higher rate. At 3%, an extra dollar saves about 60 cents. At 8%, it saves $2.65.
"Interest saved per dollar" isn't a return you can compare directly with the stock market. The savings arrive slowly, over decades. A better way to think about it: paying down a loan at 6.5% earns about 6.5% a year, guaranteed and untaxed. Whether that beats investing depends on what you'd earn instead, after tax. Our guide on paying off a mortgage early works through that comparison, including the break-even return.
5. Other ways to make extra payments
- One extra payment a year. Adding one-twelfth of your payment ($158.02) to each month does the same job as a 13th payment. On the example loan it takes 5 years 10 months off and saves $87,258.
- A yearly lump sum. $3,000 once a year, from a bonus or tax refund, saves $116,053 and 8 years. $250 a month, the same amount spread out, saves $120,339 and 8 years 2 months. Paying sooner beats paying later, but the gap is small, so use whichever fits your cash flow.
- Rounding up. Paying $1,900 instead of $1,896.20 is the easiest version, if your lender lets you.
6. Before you start
- Tell the lender the extra is for principal. Some servicers hold unlabeled money toward next month's payment, which saves nothing. Check your next statement.
- Check for a prepayment penalty. Most home loans today don't have one, but some do. Your loan documents will say.
- Keep an emergency fund. Money sent to the loan is hard to get back without borrowing again.
- Pay off higher-rate debt first, and take any employer 401(k) match.
- If you pay PMI, extra payments also bring forward the day you can cancel it. See our guide on getting rid of PMI.
Try it with your numbers
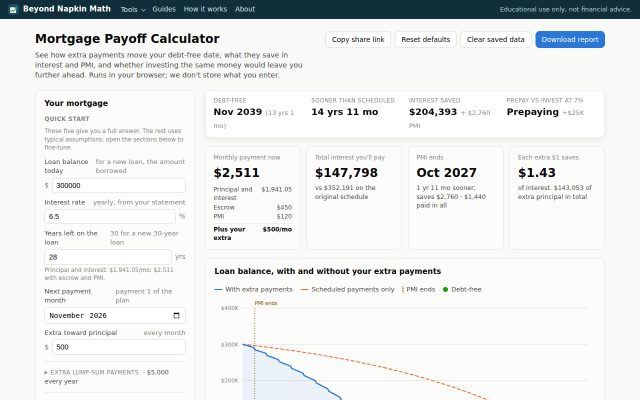
The Mortgage Payoff Calculator opens with this example. Enter your own balance, rate, years left and extra payment. It shows your debt-free date and the interest saved, splits the effect of monthly extras and lump sums, and compares prepaying with investing. It runs in your browser and we don't store your numbers.
 Run your own numbers
Mortgage Payoff Calculator
Extra payments, PMI and the real question: pay it down or invest?
Open the tool →