Does buying a home save tax in 2026? The itemizing test
"You'll get a tax break on the interest" is one of the most repeated reasons to buy. For most households it's wrong, or much smaller than people think. Mortgage interest only saves tax if your itemized deductions beat the standard deduction, and only by the amount they beat it. In 2026 the standard deduction for a married couple is $32,200.
1. The itemizing test
You can take the standard deduction or add up your itemized deductions, whichever is larger. A homeowner's itemized deductions are mainly:
- Mortgage interest on up to $750,000 of loan used to buy the home.
- State and local taxes (SALT): property tax plus state income tax, capped at $40,400 in 2026. The cap shrinks for incomes over $505,000 (not below $10,000), rises 1% a year through 2029, then drops back to $10,000 in 2030.
- Mortgage insurance (PMI), deductible again from 2026 as mortgage interest. But it's reduced 10% for every $1,000 of income over $100,000, so it's gone by $110,000.
- Charitable gifts and a few others.
The tax saving is the excess over the standard deduction times your tax rate, not your whole interest bill times your rate. A renter also has state income tax to deduct, but rarely enough to itemize.
2. Seven households, year one
Each buys with 20% down at 6.5% (one with 10% down), with property tax of 1.1% and 5% state income tax unless noted. The Rent vs Buy Calculator compares the tax each would owe as an owner against renting:
| Household | Itemized deductions | Standard deduction | Tax saved, year one |
|---|---|---|---|
| Married, $120,000 income, $400,000 home | $31,095 | $32,200 | $0 |
| Same, but no state income tax | $25,095 | $32,200 | $0 |
| Same, but 10% down (with PMI) | $33,682 | $32,200 | $178 |
| Single, $120,000 income, $400,000 home | $31,095 | $16,100 | $3,299 |
| Married, $180,000 income, $600,000 home | $46,642 | $32,200 | $3,177 |
| Married, $250,000 income, $800,000 home | $62,689 | $32,200 | $6,836 |
| Same, with 9% state income tax | $72,689 | $32,200 | $9,036 |
The typical married couple buying a $400,000 home gets nothing: $20,695 of first-year interest plus property and state tax still falls short of the standard deduction. The PMI deduction doesn't help them either, because at $120,000 of income it has phased out. Single buyers, whose standard deduction is half as large, and larger loans in high-tax states, benefit most.
The saving also shrinks over time. Interest falls each year as the loan is paid down, while the standard deduction rises with inflation.
3. The common mistake
The $250,000 household pays $41,389 of interest in year one. The quick estimate "interest × their 22% tax bracket" says that saves $9,106. The real saving is $6,836, because the first $32,200 of deductions would have been free with the standard deduction anyway.
4. What this means for rent vs buy
For the typical household, owning has to win on its own merits: price growth, loan paydown, a fixed payment. The tax break isn't a reason to buy. For single buyers and larger loans, the saving is real and shortens the time it takes owning to beat renting. In the calculator, the married $400,000 buyer breaks even in year 9; the single buyer with the same home, in year 5. Our guide Rent or buy in 2026 covers the full comparison.
5. Other tax rules for owners
- Selling: up to $250,000 of gain ($500,000 married) is tax-free after you've owned and lived in the home for 2 of the last 5 years.
- Points you pay to buy a home are generally deductible as interest, if you itemize.
- Home office, energy credits and other rules exist but aren't modeled here.
Try it with your numbers
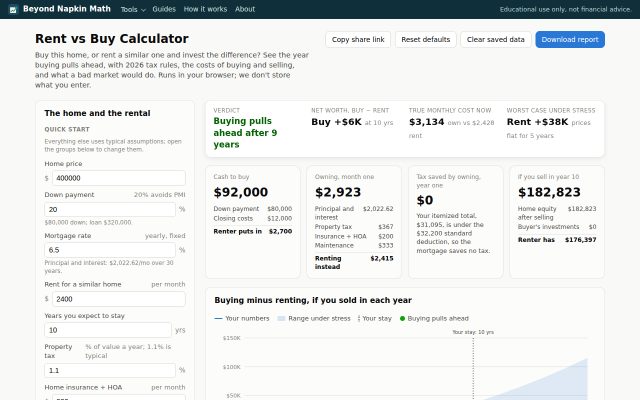
The Rent vs Buy Calculator opens with the $800,000 example. Under "Taxes", set your filing status, state income tax rate and other itemized deductions. It runs the itemizing test every year and shows whether you itemize and what the mortgage really saves. It runs in your browser and we don't store your numbers.
Educational only, not tax advice. Tax software or a tax professional can confirm your own situation.
More guides for this tool
- "Rent is throwing money away": what the numbers say
- Rent or buy in 2026: why the break-even is longer than you think
- Should you buy a home if you'll only stay five years?
 Run your own numbers
Rent vs Buy Calculator
After how many years does buying beat renting and investing the difference?
Open the tool →